
Utility-Scale Renewables, BESS Storage & Clean Infrastructure Financing
Structuring non-recourse project finance facilities, turbine and photovoltaic capex term debt, and grid interconnection bridge liquidity across utility solar, onshore wind, battery energy storage systems (BESS), and industrial decarbonisation assets.
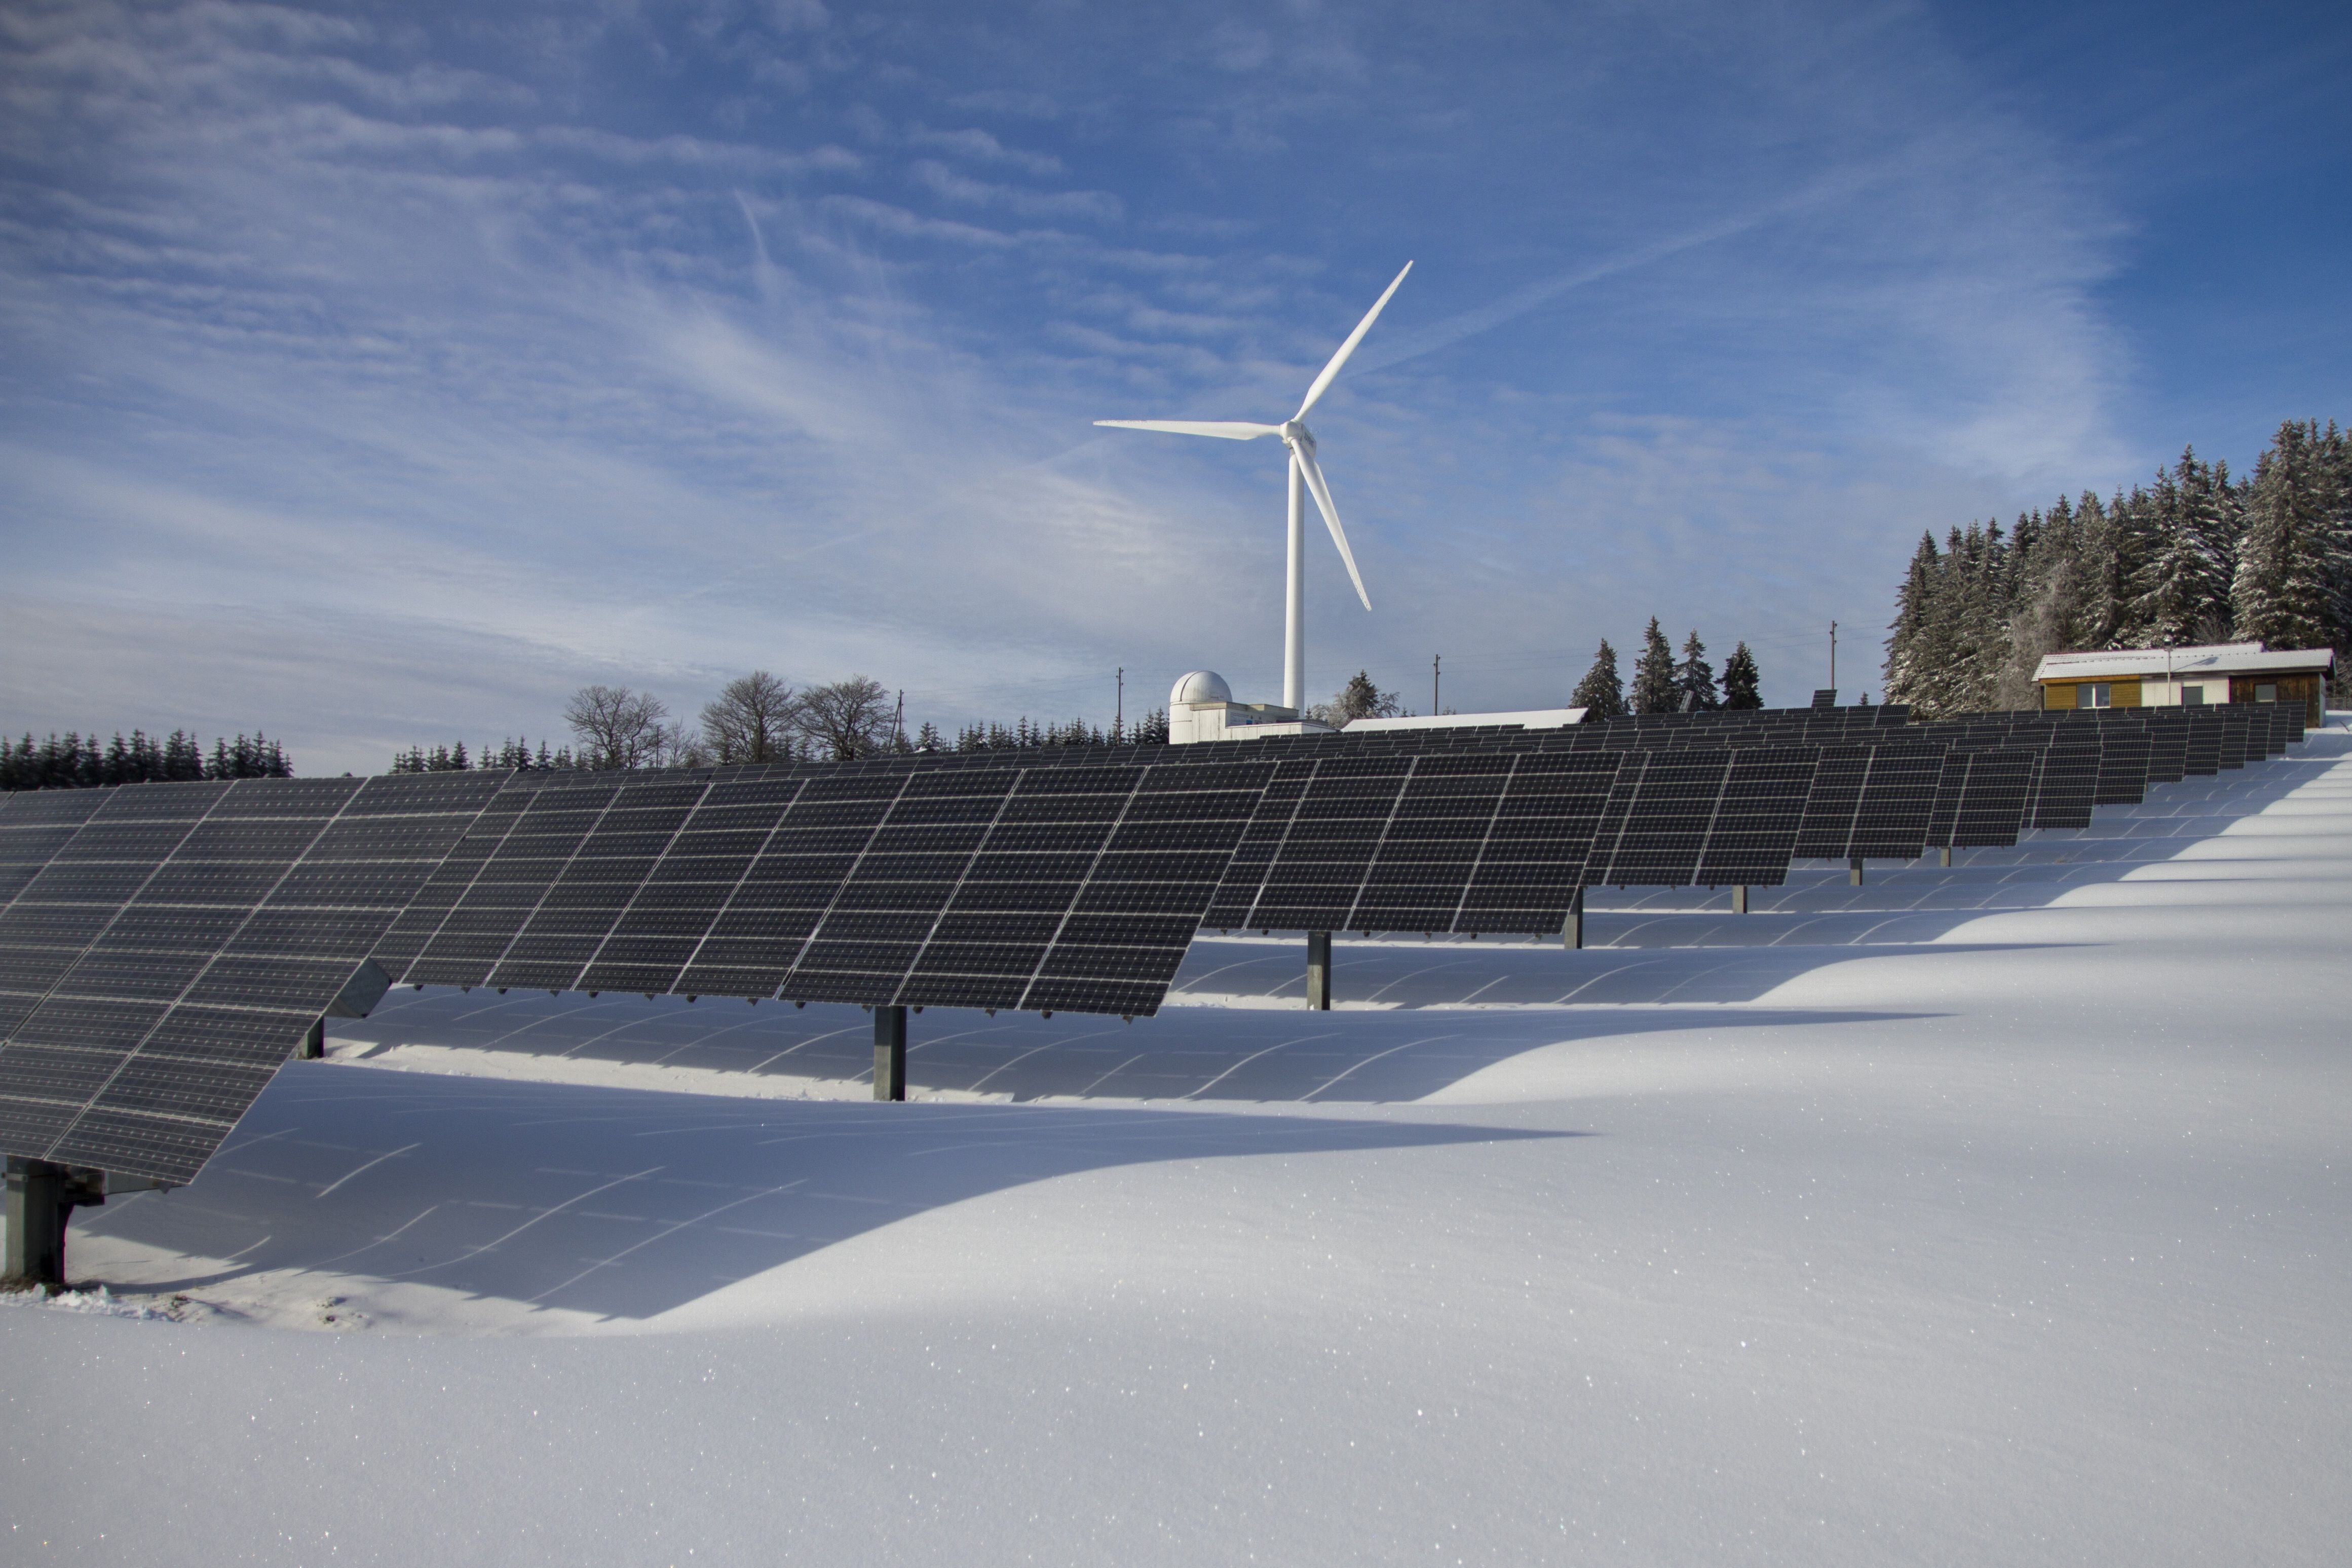
Renewable Energy & Decarbonisation Economics
The global energy transition requires unprecedented capital mobilization. Utility-scale solar photovoltaic parks, onshore and offshore wind farms, utility-scale battery storage (BESS), and green industrial microgrids require debt structures that reflect the unique physical physics of energy yield, weather intermittency, and power off-take contracts.
Commercial banks frequently evaluate renewable energy projects with generic real estate or corporate lending models, creating acute funding bottlenecks around grid interconnection queues, battery cell warranty cycles, or merchant market tail risk. Bayswater Transflow structures institutional project finance anchored to bankable long-term off-take agreements and ring-fenced project SPVs.
P90 vs. P50 Resource Uncertainty Modeling
ISolar irradiance and wind flow fluctuate across seasons and multi-year climate cycles. While equity sponsors model financial returns on a median P50 probability basis, institutional credit must be underwritten to conservative P90 or P99 exceedance probabilities. Bayswater sizes debt quantum so that the project achieves a minimum 1.25x Debt Service Coverage Ratio (DSCR) even under historically depressed weather conditions.
Contracted PPA Floor vs. Merchant Power Tail
IIThe bedrock of renewable debt capacity is the Power Purchase Agreement (PPA) or Contract for Difference (CfD). Long-tenor 15-year contracts with investment-grade corporate off-takers or state utilities provide guaranteed strike prices, shielding debt service from spot electricity price volatility. Any unhedged merchant volume is modeled as subordinate upside cash flow.
Equipment Degradation & Battery Augmentation Reserves
IIIPhotovoltaic solar panels experience 0.5% annual efficiency degradation, while lithium-ion BESS battery systems experience cell capacity fade over 7 to 10-year cycling lifespans. Bayswater mandates structured Major Maintenance Reserve Accounts (MMRA) and contractual battery augmentation funds, ensuring capital is accumulated to replace degraded battery racks without violating loan covenants.
Non-Recourse SPVs & Escrow Cash Waterfalls
IVEach generation asset is ring-fenced into a dedicated special purpose vehicle (SPV) with zero recourse to the sponsor balance sheet post-commissioning. All electricity grid revenues flow into a Trust and Retention Account (TRA) governed by an independent security trustee, ensuring operating maintenance and senior debt service take absolute priority over equity distributions.
Engineering Milestones, Grid Integration & Cash Generation
Renewable energy projects transition through six distinct operational phases, moving from environmental resource modeling to full commercial dispatch:
Non-Recourse Project SPV & PPA Cash Waterfall Architecture
Visualizing how non-recourse project debt, EPC warranties, corporate off-take contracts, and automated escrow sweeps integrate into an institutional clean energy financing structure:
graph TD
    subgraph ProjectVehicle ["1. Ring-Fenced Generation Asset"]
        SPV["Renewable Project SPV
Owns Solar Park, Wind Turbines & BESS
Bankruptcy-Remote Legal Entity"]
        EPC["Tier-1 EPC & O&M Contractor
Turnkey Wrap + Performance Liquidated Damages"]
        Offtaker["Corporate / Utility Off-Taker
15-Year Take-or-Pay PPA / CfD Contract"]
    end

    subgraph DebtArchitecture ["2. Bayswater Structured Clean Energy Stack"]
        SeniorDebt["Tranche A: Senior Non-Recourse Project Debt
70-75% Capex | SOFR + 350 bps | 15-Yr Amortising
First Fixed Charge on Equipment, Land & PPA"]
        MezzClean["Tranche B: Green Mezzanine / Subordinated Notes
10% Capex | 10.5% Cash + PIK Margin
Subordinated Charge & Sponsor Equity Pledge"]
        Equity["Sponsor Equity Commitment
15-20% Cash Equity Invested Upfront"]
    end

    subgraph EscrowWaterfall ["3. TRA Revenue Collection & Escrow Waterfall"]
        Remittances["PPA Generation Revenues & Grid Settlement
Deposited Directly into Trust and Retention Account (TRA)"]
        Sweep1["Priority 1: Statutory Taxes & Essential O&M Costs"]
        Sweep2["Priority 2: Senior Project Debt Service (Principal & Interest)"]
        Sweep3["Priority 3: 6-Month Debt Service Reserve Account (DSRA)"]
        Sweep4["Priority 4: Subordinated Mezzanine Note Coupon"]
        Sweep5["Priority 5: Major Maintenance Reserve Account (MMRA / BESS Augmentation)"]
        Sweep6["Priority 6: Sponsor Equity Dividend Distribution"]
    end

    SPV --- EPC
    SPV --- Offtaker
    SeniorDebt --> SPV
    MezzClean --> SPV
    Equity --> SPV

    Remittances --> Sweep1
    Sweep1 --> Sweep2
    Sweep2 --> Sweep3
    Sweep3 --> Sweep4
    Sweep4 --> Sweep5
    Sweep5 --> Sweep6
Worked Financial Exhibit: 120MW Solar PV & 40MWh BESS Plant Gearing
The schedule below models generation yield, PPA strike rates, operating costs, and Debt Service Coverage Ratios (DSCR) for an institutional $90,000,000 co-located solar and storage asset carrying $65M in senior debt across varying exceedance probabilities:
| Yield Case | Annual Generation | Blended PPA Rate | Gross Revenue | O&M Expenses | Operating CFADS | Senior Debt Service | Calculated DSCR |
|---|---|---|---|---|---|---|---|
| Severe Weather (P99) | 168.0 GWh | $68.50 / MWh | $11,508,000 | $2,450,000 | $9,058,000 | $7,350,000 | 1.23x (Stress Floor) |
| Underwriting Case (P90) | 185.0 GWh | $68.50 / MWh | $12,672,500 | $2,480,000 | $10,192,500 | $7,350,000 | 1.39x (Base Underwriting) |
| Median Base Case (P50) | 204.0 GWh | $68.50 / MWh | $13,974,000 | $2,520,000 | $11,454,000 | $7,350,000 | 1.56x (Healthy Coverage) |
| High Resource Year (P10) | 222.0 GWh | $68.50 / MWh | $15,207,000 | $2,560,000 | $12,647,000 | $7,350,000 | 1.72x (Strong Free Cash) |
| P50 + Ancillary Grid Arbitrage | 204.0 GWh + BESS | $74.20 / MWh | $15,136,800 | $2,640,000 | $12,496,800 | $7,350,000 | 1.70x (Peak Revenue Mix) |
Tailored Debt Instruments for Clean Energy Assets
Bayswater Transflow structures three distinct capital solutions matched to the construction, generation, and storage phases of renewable assets:
Non-Recourse Project Debt
Long-tenor senior debt financing construction and term operations, amortised directly from contracted PPA and Capacity Market cash flows.
Pricing: SOFR + 325-425 bps
Tenor: Construction + 15-Year Term
Turbine & BESS Capex Lines
Specialized equipment capex facilities funding high-efficiency solar modules, wind turbine drivetrains, and Year-7 battery rack augmentation rounds.
Security: First Chattel Mortgage on Cells
Pricing: SOFR + 375-475 bps
Grid Deposit & LC Bridges
Standby letters of credit and bridge liquidity satisfying Transmission System Operator (TSO) grid security deposits without tying up cash equity.
Fee Structure: 1.75% to 2.50% p.a.
Release: Upon Grid COD Energization
Institutional Credit Committee Diligence Perimeter
Credit underwriting for utility-scale energy transition infrastructure requires rigorous technical, commercial, and legal due diligence:
Lender's Technical Advisor (LTA)
Engagement of globally recognized technical consultants (DNV, Wood, Arup) to audit solar irradiance, wind anemometry, terrain wake loss, and curtailment risk to establish bankable P90 cash flow models.
OEM Equipment Warranties
Verification of BloombergNEF Tier-1 solar module, inverter, and battery cell manufacturers. Review of 25-year linear power warranties, availability guarantees (> 97%), and parent guarantee balance sheets.
TSO Curtailment & Connection
Verification of firm grid export capacity rights, substation transformer energization timeline, network constraint study, and curtailment compensation clauses in the connection agreement.
PPA Credit & Termination Risk
Forensic analysis of corporate off-taker credit ratings (S&P / Moody's), contractual step-in rights, force majeure provisions, deemed generation clauses, and early termination make-whole damages.
Trust & Retention Account (TRA)
Establishment of institutional TRA bank accounts governed by a tri-partite agreement between SPV, Account Bank, and Security Trustee, ensuring complete control over electricity settlement cash flows.
Decommissioning & Equator Principles
Compliance with Equator Principles IV and IFC Performance Standards. Structuring sinking fund reserves during the final 10 years of project life to finance site remediation and decommissioning bonds.
Executed Debt Structures & Indicative Case Mandates
Indicative transaction archetypes reflecting Bayswater's structuring capabilities across utility solar, battery storage, and onshore wind generation:
$75.0M Ground-Mount Solar PV Portfolio (120 MWp)
Non-recourse construction and term project debt facility for a 120 MWp utility-scale solar photovoltaic project backed by a 15-year corporate PPA with an investment-grade technology multinational.
$42.0M Utility-Scale BESS (60MW / 120MWh)
Dual-revenue debt architecture funding a 2-hour duration lithium iron phosphate (LFP) battery facility securing contracted Capacity Market payments and merchant wholesale grid frequency response.
$95.0M Onshore Wind & Substation Infrastructure
Multi-tranche syndicated facility delivering 18 modern 4.2 MW direct-drive wind turbines and a dedicated 132kV private substation connecting directly into the transmission network.
Independent Clean Energy Debt Structuring & Advisory Role
Bayswater Transflow operates strictly as an independent corporate finance advisor, clean infrastructure debt arranger, and transaction architect. Bayswater does not provide balance-sheet lending from proprietary balance sheets, does not accept customer deposits, and does not provide regulated utility brokerage.
All modeled P90 exceedance probabilities, generation revenue schedules, and indicative project debt models are presented strictly for evaluation by qualified utility-scale renewable sponsors, institutional infrastructure funds, and accredited professional intermediaries.
Calibrate Your Renewable Project Debt Stack
Submit non-confidential project feasibility reports, PPA term sheets, or grid connection agreements for a bespoke debt capacity audit and financial sizing review.
Important Disclosure
Information
Past performance and illustrative structures do not predict future returns or guarantee transaction completion. There can be no assurance that any potential mandate will achieve intended commercial terms or that counterparties will proceed to definitive execution. All commentary discusses broad commercial, industry, or sector situations and is provided for institutional information only.
Bayswater Transflow Ltd is an independent corporate advisory and transaction origination firm registered in England and Wales (Company No. 16277213). It is not authorised or regulated by the Financial Conduct Authority (FCA) and does not conduct regulated investment business, hold client money, arrange regulated activities, or advise the retail public on investments. Definitive documentation and regulated decisions remain exclusively with authorised counterparties and appointed professional counsel.
Next step
Structure non-recourse debt for utility renewables and clean power.
Bayswater arranges bankable project debt, turbine capex facilities, and BESS storage financing anchored to long-term off-take contracts.