
Operational Economics & Capital Structuring for Life Sciences Platforms
Analyzing the heavy regulatory gestation of pharmaceutical synthesis: cleanroom validation cycles, stability testing working capital deficits, and multi-tranche debt structures that finance commercial production expansion without equity dilution.
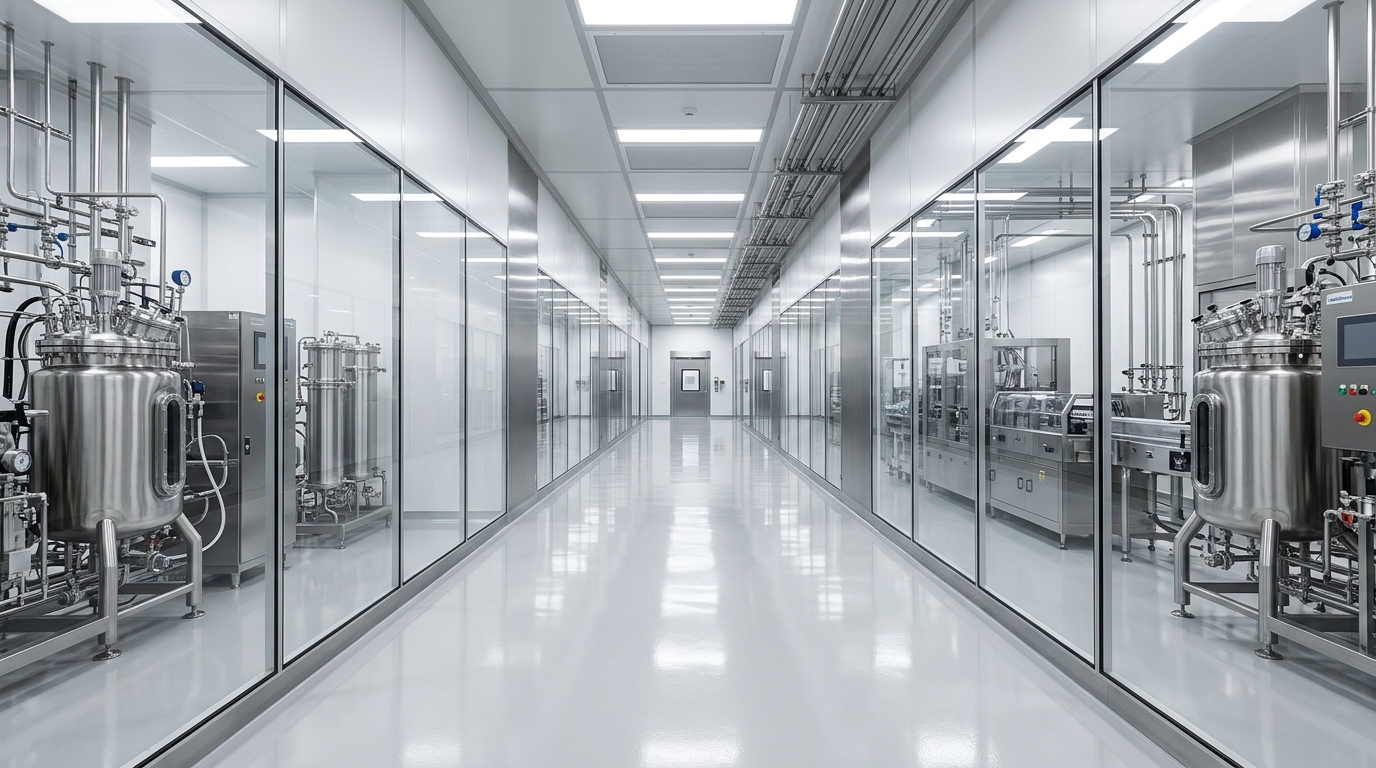
The Regulatory Gestation Runway & Cleanroom Asset Economics
Unlike standard commercial production, pharmaceutical manufacturing operates under strict regulatory friction. Commissioning an active pharmaceutical ingredient (API) synthesis suite or an aseptic sterile formulation line requires 18 to 36 months of uncompensated capital investment before commercial batch certification.
During this extended runway, capital is consumed across cleanroom civil works, terminal HEPA HVAC infrastructure, pure Water for Injection (WFI) loop generation, and mandatory Installation, Operational, and Performance Qualifications (IQ/OQ/PQ). Rigid commercial banking lines fail because they demand immediate amortisation during regulatory gestation when the plant produces zero commercial revenue.
The 120 to 180-Day Cash Conversion Gap
IPharmaceutical balance sheets carry substantial liquidity lockups. Raw chemical key starting materials (KSMs) must be procured and verified (30 days), synthesized through multiple reaction steps (30 to 45 days), and held in mandatory quarantine for microbiological sterility and stability release testing (30 to 45 days). Paired with 60 to 90-day institutional receivables, the net cash gap routinely exceeds 150 days.
Regulatory Site Lock-In & Pricing Stickiness
IIOnce an API synthesis facility or CDMO platform is formally registered in an innovator marketing dossier or Drug Master File (DMF), transferring manufacturing to an alternative site requires an 18 to 24-month regulatory variation process. This creates immense structural revenue stickiness, protecting gross margins against sudden customer turnover.
Cleanroom Asset Depreciation vs. Replacement Economics
IIIAccounting depreciation writes down pharmaceutical equipment rapidly over 5 to 7 years. In reality, certified stainless-steel glass-lined reactors, high-speed rotary tablet presses, and automated lyophilizers retain high Net Orderly Liquidation Values (NOLV) for 15 to 25 years when maintained under current Good Manufacturing Practice (cGMP) standards. Bayswater unlocks debt capacity by underwriting certified NOLV appraisals rather than historical book values.
Integrated Dual-Tranche Debt Architecture
IVBayswater Transflow structures integrated multi-tier debt facilities tailored to life sciences platforms: long-tenor senior capex loans with 18 to 24-month principal repayment holidays during cleanroom validation, paired with formulaic asset-based revolving lines secured by verified institutional receivables and validated bulk API stock. Both tranches operate seamlessly under an institutional intercreditor deed.
Cleanroom Validation Timelines & Capital Consumption Milestones
Life sciences facilities progress through a disciplined multi-stage gestation sequence before realizing commercial cash flows:
Life Sciences Production Engine & Dual-Tranche Debt Architecture
Visualizing how cleanroom physical infrastructure, validated bulk API stock, and institutional receivables integrate into an unencumbered dual-tranche debt structure:
graph TD
    subgraph CollateralBase ["1. Pharmaceutical Collateral & Asset Perimeter"]
        CleanroomPlant["Cleanroom & Processing Machinery
Lyophilizers, Isolators & Glass-Lined Reactors
Appraised at Net Orderly Liquidation Value (NOLV)"]
        ValidatedStock["Released Finished Goods & Validated APIs
Commercial Batches with >18 Months Shelf Life
Formulaic Borrowing Base Advance: 50-60% NOLV"]
        TradeReceivables["Eligible Institutional Receivables
Invoices to Global CDMO Sponsors & Public Health Buyers
Formulaic Borrowing Base Advance: 85%"]
    end

    subgraph DebtArchitecture ["2. Bayswater Arranged Multi-Tier Debt Stack"]
        TrancheA["Tranche A: Regulatory Capex Term Loan
Up to 75% NOLV | 6-8 Years | 20-Month Principal Grace
Security: Registered First Fixed Charge on Machinery"]
        TrancheB["Tranche B: Revolving Borrowing Base Line
Formulaic Working Capital Facility | SOFR + 375 bps
Security: Floating Charge on Stock & DACA Lockbox"]
    end

    subgraph WaterfallCascade ["3. Cash Realisation & Waterfall Routing"]
        SalesReceipts["Global Pharmaceutical Sales Inflows
Remitted Directly to Controlled DACA Account"]
        Step1["Priority 1: Revolving Working Capital Sweep & Liquidity Headroom"]
        Step2["Priority 2: Senior Equipment Debt Service (Interest & Post-Grace Principal)"]
        Step3["Priority 3: Manufacturer Retained Free Cash Flow & Sponsor Equity"]
    end

    CleanroomPlant --> TrancheA
    ValidatedStock --> TrancheB
    TradeReceivables --> TrancheB
    SalesReceipts --> Step1
    Step1 --> Step2
    Step2 --> Step3
Worked Financial Exhibit: Cleanroom Gestation & Cash Deficit Model
The schedule below models capital consumption, working capital absorption, and debt service coverage for a $45,000,000 sterile formulation expansion across its 36-month validation runway:
| Validation Phase | Timeline | Capex Deployed | Quarantine WIP | Commercial Revenue | Debt Service (With Grace) | Calculated Headroom |
|---|---|---|---|---|---|---|
| Phase 1: Civil & IQ/OQ | Months 1 to 12 | $18,500,000 | $0 | $0 | $780,000 (Interest Only) | $3,220,000 Liquidity |
| Phase 2: PQ Exhibit Batches | Months 13 to 18 | $4,200,000 | $3,800,000 (Locked) | $0 | $420,000 (Interest Only) | $2,100,000 Liquidity |
| Phase 3: ICH Stability Testing | Months 19 to 26 | $1,800,000 | $4,200,000 (Incubating) | $0 | $560,000 (Interest Only) | $1,540,000 Liquidity |
| Phase 4: PAI Regulatory Audit | Months 27 to 32 | $900,000 | $4,500,000 | $3,500,000 (Early Runs) | $420,000 (Interest Only) | $2,480,000 Liquidity |
| Phase 5: Full Commercial Ramp | Month 33 Onward | $600,000 (Sustaining) | $2,800,000 (Circulating) | $45,000,000 (Annualized) | $2,850,000 (P + I Amortising) | 4.25x DSCR Coverage |
Tailored Debt Instruments for Pharmaceutical Platforms
Bayswater Transflow structures three distinct capital solutions matched to the capital intensity and regulatory cycles of pharmaceutical platforms:
Regulatory Capex Term Debt
Senior secured term loans financing cleanroom suites, isolators, and chemical reactors with 18 to 24-month principal repayment holidays matching validation cycles.
Pricing: SOFR + 475-575 bps
Tenor: 6 to 8 Years Amortising
Asset-Based Formulation Revolvers
Revolving credit lines expanding dynamically with verified institutional receivables (85% advance) and validated bulk API stock (50-60% NOLV) under monthly BBC reporting.
Pricing: SOFR + 350-450 bps
Governance: Monthly BBC Reporting
Subordinated Mezzanine Notes
Junior capital funding clinical bio-equivalence studies or founding shareholder buyouts with non-dilutive PIK coupons, preserving equity upside.
Coupon: Cash Pay + PIK Toggle
Subordination: Second Fixed Charge
Institutional Credit Committee Diligence Perimeter
Life sciences underwriting requires technical regulatory verification alongside audited corporate financial reporting:
5-Year Inspection History
Comprehensive review of preceding 5 years of regulatory inspection reports (US FDA Establishment Inspection Reports EIR, Form 483s, UK MHRA and EMA audit letters) and verified close-out responses.
Out-of-Specification Investigations
Granular analysis of Out-of-Specification (OOS) batch records, microbiological environmental excursions, and historical batch rejection rates (institutional benchmark below 1.25% of completed runs).
21 CFR Part 11 Systems
Technical audit of automated audit trails and access hierarchies on laboratory High-Performance Liquid Chromatography (HPLC), mass spectrometers, and SCADA building management systems.
Quality Technical Agreements
Review of Quality Technical Agreements (QTAs) with CDMO clients to verify that manufacturer liability for contaminated or out-of-spec batches is strictly capped at raw material replacement costs.
ASA / RICS Machinery Valuation
On-site physical inspection and certified Net Orderly Liquidation Value (NOLV) appraisal of stainless reactors, automated filling lines, and lyophilizers by accredited life sciences appraisers.
Lockbox Cash Dominion
Perfection of Deposit Account Control Agreements (DACA) over pharmaceutical debtor proceeds, excluding unreleased quarantine stock from eligible collateral until formal QP release certification.
Representative Life Sciences Facility Architectures
The indicative structural models below illustrate how Bayswater Transflow structures debt capacity across pharmaceutical and API manufacturing sub-sectors:
$45.0M Sterile Lyophilisation Suite Expansion
Dual-tranche facility for an aseptic injectable manufacturer constructing a Grade A cleanroom suite, automated vial filling line, and industrial freeze-dryers for European CDMO contracts.
$28.0M High-Potency API (HPAPI) Block
Equipment term loan and bulk chemical inventory borrowing base for an oncology API producer installing high-containment reaction isolators and solvent distillation units.
$20.0M Oral Dosage CDMO Recapitalisation
Senior debt and subordinated mezzanine package funding a founder equity buyout while refinancing high-speed rotary tablet presses and blister packaging automation.
Independent Debt Architecture & Corporate Advisory Role
Bayswater Transflow operates exclusively as an independent corporate finance advisor, transaction architect, and private debt arranger. Bayswater does not provide balance-sheet lending from proprietary reserves, does not conduct pharmaceutical regulatory certification, and does not conduct regulated retail banking or public securities underwriting.
All cleanroom validation timelines, worked financial models, advance rate benchmarks, and indicative transaction structures are presented strictly for professional evaluation by eligible life sciences platforms, CDMO sponsors, institutional credit managers, and accredited professional intermediaries.
Calibrate Your Pharmaceutical Capital Stack
Submit non-confidential cleanroom capex budgets, IQ/OQ validation schedules, and customer CDMO supply agreements for an initial equipment debt and inventory borrowing base review.
Important Disclosure
Information
Past performance and illustrative structures do not predict future returns or guarantee transaction completion. There can be no assurance that any potential mandate will achieve intended commercial terms or that counterparties will proceed to definitive execution. All commentary discusses broad commercial, industry, or sector situations and is provided for institutional information only.
Bayswater Transflow Ltd is an independent corporate advisory and transaction origination firm registered in England and Wales (Company No. 16277213). It is not authorised or regulated by the Financial Conduct Authority (FCA) and does not conduct regulated investment business, hold client money, arrange regulated activities, or advise the retail public on investments. Definitive documentation and regulated decisions remain exclusively with authorised counterparties and appointed professional counsel.
Next step
Structure debt aligned with regulatory validation.
Bayswater arranges long-tenor capex facilities with repayment grace periods and inventory lines to support life sciences expansion without liquidity strain.
