
Automotive OEM Tier-1 Supply Chains & Mobility Capex Architecture
Structuring progressive tooling term debt, automated stamping and robotic cell asset-based facilities, and Electronic Data Interchange (EDI) debtor discounting lines for Tier-1 automotive component producers and electric vehicle mobility manufacturers.
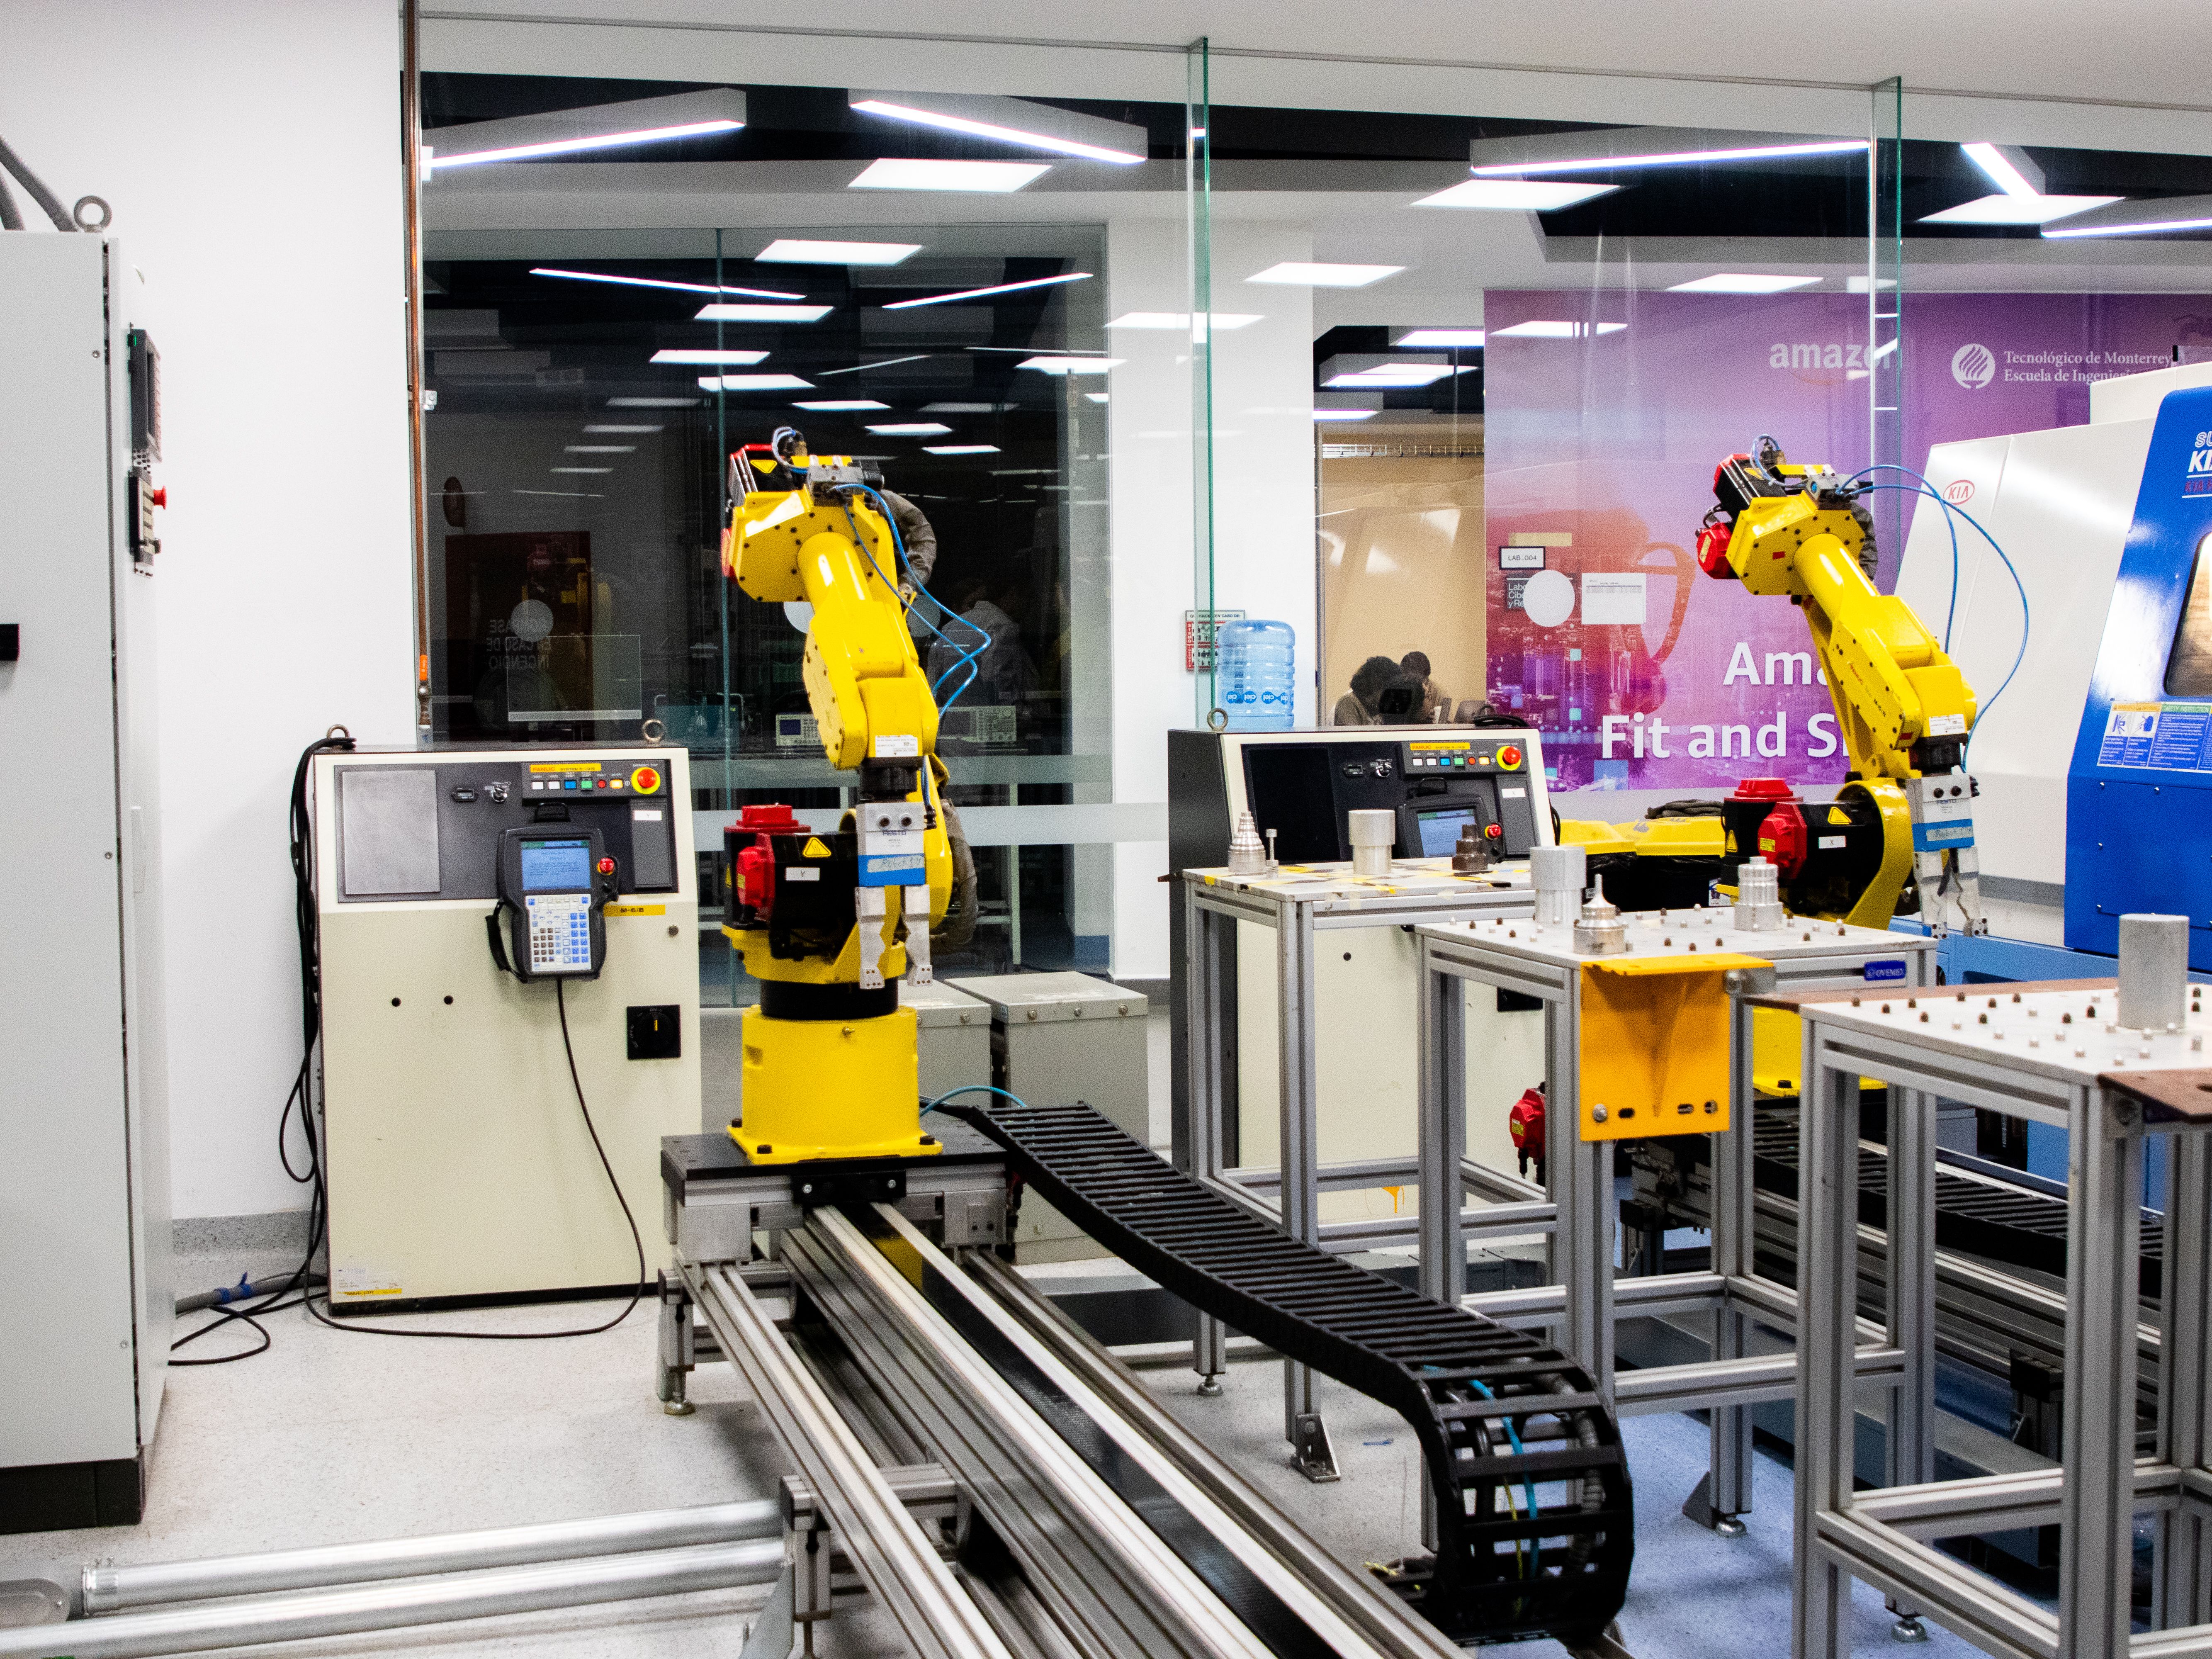
Automotive OEM Tier-1 Supply Chain Economics
The automotive and mobility manufacturing sector operates under the most demanding technical and contractual regimes in industrial engineering. Tier-1 and precision Tier-2 component producers supply global vehicle original equipment manufacturers (OEMs) across multi-year vehicle platform life cycles spanning 5 to 7 years.
Before series production delivers cash flow, suppliers face intense upfront engineering and capital expenditures: custom stamping dies, progressive injection moulds, multi-axis robotic welding cells, and PPAP Level 3 statistical validation runs. Bayswater Transflow structures specialized private debt facilities that finance production readiness and machinery capex without requiring dilutive equity capital.
Multi-Year Platform Cycles: SOP to EOP Dynamics
IVehicle platform contracts run from Start of Production (SOP) to End of Production (EOP) over 5 to 8 years. While contracts specify indicative annual volumes, OEMs do not commit to rigid take-or-pay volumes, relying instead on rolling weekly Electronic Data Interchange (EDI) delivery schedules. Debt must be sized to withstand temporary OEM production line shutdowns without breaching cash flow covenants.
Tooling Amortisation Cash Deficits & PPAP Validation
IIProduction Part Approval Process (PPAP Level 3) mandates statistically validated pilot manufacturing runs (Cpk > 1.67) that take 6 to 12 months. Dedicated progressive dies and fixtures ($1M to $10M+) must be financed months before the OEM reimburses tooling capex via lump-sum audit approval or per-part amortisation adders. Bayswater arranges dedicated tooling bridge lines that liquidate upon PPAP sign-off.
Contractual Price-Down Mandates & Scrap Indexation
IIIAutomotive master contracts enforce contractual 2% to 3% annual productivity price reductions. Component manufacturers protect margins by investing in automated robotic handling and closed-loop scrap recycling. Raw steel, aluminium, and technical resin price fluctuations are hedged via contractual indexation formulas that adjust unit part prices quarterly.
Dual-Tranche Capital: Fixed Machinery & Dynamic Revolvers
IVBayswater integrates long-tenor term debt secured by independent Net Orderly Liquidation Value (NOLV) appraisals on stamping presses and laser welding cells, paired with formulaic asset-based revolving credit lines secured by verified raw metal stores and EDI debtor accounts. Both tranches operate under institutional intercreditor priority deeds.
Platform Nomination, Tooling Tryout & Series Production
Automotive Tier-1 suppliers navigate six rigorous milestones, progressing from commercial bidding to full-rate production line call-offs:
Tier-1 Automotive Capital Engine & Multi-Tier Cash Flow
Visualizing how stamping press capex, raw metal inventory, and OEM portal receivables integrate into an institutional dual-tranche credit structure:
graph TD
    subgraph OperationalAssets ["1. Physical Plant & Operating Collateral Pools"]
        StampingPresses["High-Tonnage Press Lines & Robotic Welding Cells
Servo Presses & Automated Assembly Fixtures
Underwritten to Net Orderly Liquidation Value (NOLV)"]
        RawAlloy["Certified Steel Coils & VMI Buffer Hub Stores
Automotive-Grade Alloys & Unassembled Stampings
Formulaic Borrowing Base Advance: 60-70% NOLV"]
        EDIDebtors["Eligible Global OEM Trade Receivables
Electronic Data Interchange (EDI) Validated Call-Offs
Formulaic Borrowing Base Advance: 85%"]
    end

    subgraph DebtArchitecture ["2. Bayswater Arranged Dual-Tranche Stack"]
        TrancheA["Tranche A: Senior Machinery & Tooling Capex Loan
Up to 80% NOLV | 6-Yr Amortising | SOFR + 495 bps
Security: Registered First Chattel Mortgage"]
        TrancheB["Tranche B: Formulaic Borrowing Base Revolver
Dynamic Working Capital Line | SOFR + 395 bps
Security: Qualifying Floating Charge & DACA Lockbox"]
    end

    subgraph CashRouting ["3. Revenue Realisation & Waterfall Distribution"]
        OEMRemittances["Global OEM Portal Electronic Payments
Remitted Directly to Controlled DACA Escrow Account"]
        Sweep1["Priority 1: Revolving Line Working Capital Sweep & Dynamic Re-Advance"]
        Sweep2["Priority 2: Senior Equipment Debt Service (Quarterly Principal & Interest)"]
        Sweep3["Priority 3: Operator Retained Operating Margin & Equity Cash Flow"]
    end

    StampingPresses --> TrancheA
    RawAlloy --> TrancheB
    EDIDebtors --> TrancheB

    OEMRemittances --> Sweep1
    Sweep1 --> Sweep2
    Sweep2 --> Sweep3
Worked Financial Exhibit: Operating Leverage & Debt Service Capacity
The schedule below models how factory shift capacity utilization dictates gross margin, EBITDA, and Debt Service Coverage Ratio (DSCR) for a $75,000,000 top-line automotive Tier-1 supplier carrying $28.0M in total credit facilities:
| Shift Utilization | Annual Turnover | Gross Margin | Fixed Overheads | Operating EBITDA | Debt Service | Calculated DSCR |
|---|---|---|---|---|---|---|
| 55% (Single Shift) | $41,250,000 | 11.0% ($4.54M) | $4,200,000 | $337,500 | $3,150,000 | 0.11x (Default Zone) |
| 70% (Two Shifts) | $52,500,000 | 17.5% ($9.19M) | $4,500,000 | $4,687,500 | $3,150,000 | 1.49x (Breakeven Clear) |
| 82% (Baseline Shift) | $61,500,000 | 22.0% ($13.53M) | $4,800,000 | $8,730,000 | $3,150,000 | 2.77x (Institutional Standard) |
| 94% (Full Three Shifts) | $70,500,000 | 26.5% ($18.68M) | $5,200,000 | $13,482,500 | $3,150,000 | 4.28x (Peak Cash Flow) |
Tailored Debt Instruments for Automotive & Mobility
Bayswater Transflow structures three distinct capital solutions matched to the physical plant, tooling gestation, and EDI receivables cycles of mobility suppliers:
Machinery Capex Term Loans
Long-tenor senior debt financing transfer presses, high-pressure die casting machines, and robotic assembly cells underwritten to Net Orderly Liquidation Value.
Pricing: SOFR + 450-550 bps
Tenor: 5 to 7 Years Amortising
Tooling Bridge Facilities
Milestone bridge debt covering upfront die tooling design and prototype fabrication, automatically retiring upon OEM PPAP Level 3 approval and tooling reimbursement.
Pricing: SOFR + 425-500 bps
Repayment: Direct OEM Tooling Remittance
Borrowing Base Revolvers
Dynamic asset-based revolvers expanding against raw automotive steel and aluminium stock (65% NOLV) and verified OEM EDI trade receivables (85% advance).
Pricing: SOFR + 350-425 bps
Governance: Monthly BBC & Lockbox
Institutional Credit Committee Diligence Perimeter
Credit underwriting for automotive component manufacturers evaluates plant operational quality, tooling ownership rights, and secondary equipment liquidity:
IATF 16949 & Process Control
Mandatory audit of current IATF 16949 certification, customer defect parts per million (PPM < 20), Statistical Process Control (SPC) charts, and PPAP Level 3 documentation records.
Tooling Bailment & Ownership
Clear legal distinction between customer-owned tooling held under formal bailment agreements and supplier-owned proprietary machinery, ensuring security charges attach cleanly to eligible collateral.
Platform Diversification & Life
Audit of customer debtor concentration across global OEM platforms (BMW, Stellantis, Volkswagen, Toyota, Tesla). Evaluation of vehicle model sales trajectory and remaining years to End of Production (EOP).
Independent NOLV Appraisals
Third-party physical machinery appraisals (Hilco, Gordon Brothers) determining Net Orderly Liquidation Values for transfer presses and CNC equipment in the secondary European and North American industrial markets.
Dilution & Chargeback History
Historical analysis of OEM debit memos, quality claims, warranty chargebacks, and annual price-down deductions. Dilution reserves are sized formulaically within the Borrowing Base Certificate.
EDI Integration & Lockbox Accounts
Direct electronic integration with supplier EDI portals to cross-verify physical shipping advice against OEM self-billing vouchers, remitted directly into DACA-governed trust collection accounts.
Executed Debt Structures & Indicative Case Mandates
Indicative transaction archetypes reflecting Bayswater's structuring capabilities across automotive stamping, electric vehicle powertrains, and precision casting:
$28.0M EV Aluminium Battery Tray Extrusion Line
Dual-tranche facility for an automotive Tier-1 supplier delivering high-pressure aluminium extrusion presses, automated friction stir welding, and raw alloy revolving lines for EV skateboard platforms.
$36.0M Transmission Case Die-Casting & CNC Cell
Senior equipment capex facility funding 4,000-tonne automated die-casting machines and 12 flexible CNC machining centers dedicated to hybrid powertrain transmission programs.
$18.5M Robotic Chassis Stamping & Laser Welding
Tooling bridge and equipment line for a structural chassis component stamper fulfilling high-strength steel side-member assemblies for European commercial vans.
Independent Debt Architecture & Corporate Advisory Role
Bayswater Transflow operates exclusively as an independent corporate finance advisor, debt arranger, and private transaction architect. Bayswater does not provide balance-sheet lending from proprietary reserves, does not hold deposit accounts, and does not conduct regulated consumer or retail financing.
All worked capacity models, advance rate benchmarks, NOLV illustrations, and indicative transaction models are presented strictly for professional evaluation by eligible middle-market automotive suppliers, private equity sponsors, institutional credit managers, and accredited intermediaries.
Calibrate Your Mobility Capital Stack
Submit non-confidential OEM nomination letters, machinery appraisal registers, or tooling milestone schedules for a sector-calibrated balance sheet debt review.
Important Disclosure
Information
Past performance and illustrative structures do not predict future returns or guarantee transaction completion. There can be no assurance that any potential mandate will achieve intended commercial terms or that counterparties will proceed to definitive execution. All commentary discusses broad commercial, industry, or sector situations and is provided for institutional information only.
Bayswater Transflow Ltd is an independent corporate advisory and transaction origination firm registered in England and Wales (Company No. 16277213). It is not authorised or regulated by the Financial Conduct Authority (FCA) and does not conduct regulated investment business, hold client money, arrange regulated activities, or advise the retail public on investments. Definitive documentation and regulated decisions remain exclusively with authorised counterparties and appointed professional counsel.
Next step
Structure debt for automotive stamping and EV mobility capex.
Bayswater arranges machinery NOLV term loans, tooling bridge debt, and borrowing base lines without equity dilution.